
The Shocking Bill That Opened My Eyes to the Credit Trap
Opening a car insurance renewal notice and seeing your rate spike for no apparent reason is a deeply frustrating experience. You have a clean driving record, yet your bills keep climbing. The culprit is often hidden in plain sight: your credit history. Let’s break down how credit-based insurance scores work and how you can fix your credit to drop those monthly bills.
When I called my agent to complain, she asked me a question that caught me off guard. She asked if my credit score had dropped recently. I did not understand what my credit card habits had to do with my driving safety.
That conversation changed everything for me. I learned that insurance companies look at our credit history to decide how risky we are. This means a poor score can cost you a lot of money every single year.
Quick Action Takeaways
-
Credit affects insurance: Insurers use credit-based insurance scores to predict claim risks, meaning low scores equal higher premiums.
-
Utilization matters most: Keeping your credit card balances below 10% to 30% of your total limit drastically improves your rating profile.
-
Shop around after fixing: Once your credit score climbs, proactively ask your insurer to re-evaluate your rate or switch providers for better deals.
Why Your Credit Health Secretly Rules Your Insurance Costs
Many people do not realize how much this issue affects their daily lives. You might be struggling to pay your monthly bills, skipping small luxuries just to make ends meet. Yet, you are paying a hidden tax just because your credit report has a few dark spots.
This hidden cost can feel like a heavy weight on your chest every month. It makes you feel trapped, especially when you are doing everything else right. You drive safely, lock your doors, and take care of your home, but the bills stay high.
It is incredibly frustrating to pay more for the exact same coverage as your neighbor. This struggle is real for millions of hard-working people who are trying their best. But once you understand how the system works, you can fight back and win.
The truth is that insurance companies use a special rating called a credit-based insurance score [1]. They believe that people with lower credit scores are more likely to file claims [1]. Whether this is fair or not, it is the system we have to deal with [1].
The good news is that you do not have to accept these high rates forever. Your credit score is not set in stone, and you can change it with some focus. By taking control of your credit, you can put that extra money back into your own pocket.
The Science Behind Credit-Based Insurance Scores
To beat the system, we must first understand how insurance companies think. They do not look at your regular credit score in the same way a bank does. Instead, they use your credit data to predict the likelihood of an insurance loss.
Statistical studies show a strong link between credit history and insurance claims. Actuaries have found that people who manage their money well tend to manage other risks well too. This is why a solid credit history makes you look like a safe bet.
If you have a high score, insurers see you as a low-risk client. They reward this low risk by offering you much lower annual premiums. If your score is low, they offset their perceived risk by charging you more.
How to Find and Fix Costly Errors on Your Credit Report
The very first step to fixing this problem is to look at your credit report. You cannot fix what you do not know is broken. You can get a free copy of your report from the three main credit bureaus.
Once you have your reports, look through them with a magnifying glass. Look for mistakes like accounts you never opened or late payments that you actually paid on time. Even a tiny mistake can drag your score down by dozens of points.
If you find an error, you must dispute it immediately with the credit bureau. They are required by law to investigate and remove incorrect information. Fixing just one major error can give your score a quick and massive boost.
The Simple Strategy to Master Your Monthly Payment History
Your payment history is the single biggest factor in your credit score. If you pay your bills late, your score will take a painful hit. To avoid this, you need to make on-time payments your top priority.
An easy way to do this is to set up automatic payments for all your bills. This ensures you never miss a due date, even when your life gets busy. Even paying the minimum amount on time keeps your credit record clean.
If you struggle to remember dates, use calendar reminders on your phone. Keeping a simple paper calendar on your wall can also help you stay on track. Consistently paying on time builds a strong foundation for a great credit score.
To see how this works in real life, watch this helpful explanation on how credit scores directly impact your auto insurance premiums.
Real-World Experience: A friend of mine had a flawless driving record for ten years, but an old medical collection account dragged his credit score down into the fair range. When he compared quotes with his brother—who drove the exact same car model but had excellent credit—his annual premium was nearly $600 higher. Clearing that collection account saved him hundreds within six months.
Smart Ways to Lower Your Credit Card Balances
Another key factor is how much of your available credit you are actually using. This is known as your credit utilization ratio, and it matters a lot. If your credit cards are maxed out, your score will drop quickly.
Try to keep your balance below thirty percent of your total credit limit. If you can get it below ten percent, that is even better for your score. You can achieve this by making small, extra payments throughout the month.
Credit Utilization Target Breakdown:
-
Above 30%: High risk flag to insurers; signals potential financial distress or over-reliance on revolving debt.
-
Between 10% and 29%: Moderate safe zone; acceptable, but leaves room for potential rate optimizations.
-
Below 10%: The sweet spot; signals absolute financial discipline to credit bureaus and low-risk behavior to insurance actuaries.
Pro Tip: I used to pay my credit cards only once a month on the due date. I realized my score was low because my balances looked high when the bureaus reported them. I started paying a small amount every single week, and my score jumped thirty points in two months.
If you have some extra cash, use it to chip away at your cards with the highest rates. Keeping your balances low shows insurers that you do not rely too much on debt. This simple habit makes you look much more financially stable.
Why the Age of Your Credit Accounts Matters
Many people make the mistake of closing old credit cards once they pay them off. This can actually hurt your score instead of helping it. The length of your credit history makes up a good portion of your score.
Keep your oldest accounts open, even if you do not use them very often. Just buy a small item once in a while to keep the card active. This shows a long, stable history of managing credit over time.
Having older accounts open also helps your overall credit utilization ratio. It gives you a larger pool of available credit, which looks great to lenders. Keep those old cards safe in a drawer and let them work for you.
The Danger of Opening Too Many New Accounts At Once
Every time you apply for a new credit card or loan, a hard inquiry is made. Too many of these inquiries in a short time can scare off insurers. It makes you look like you are in financial trouble and desperately need money.
Only apply for new credit when you absolutely need to. If you are shopping around for a loan, try to do it within a short window. This way, the credit bureaus will count the searches as a single inquiry.
Keep your applications clean and spaced out over several months. This slow and steady approach protects your score from unnecessary drops. It shows that you are in control of your financial path.
How to Ask Your Insurer for a Rate Re-evaluation
Once your credit score begins to improve, do not just sit back and wait. Your insurance company will not automatically lower your rate mid-policy. You have to be proactive and ask them to check your new score.
Call your agent and tell them that your credit score has gone up. Ask them to run a new credit-based insurance score check on your account. Most companies are happy to do this to keep you as a customer.
If your current company refuses to adjust your rate, do not be afraid to shop around. Take your improved credit score to other insurance companies and get new quotes. You will likely find a company willing to give you a much better deal.
The Magic of Bundling and Other Easy Savings Tips
While you work on your credit, you can use other methods to save. One of the easiest ways is to bundle your home and auto insurance together. Most companies offer a big discount if you buy more than one policy from them.
You can also look into raising your deductibles if you have some savings. A higher deductible means you pay more out of pocket if you have an claim, but your annual premium will drop. Just make sure you have enough cash saved to cover that deductible if needed.
Ask your agent about any other discounts you might qualify for. Sometimes, simple things like paperless billing or defensive driving courses can save you money. Combine these discounts with your rising credit score to get the lowest price possible.
Building a Healthy Financial Routine for Long-Term Success
Improving your credit is not a one-time event; it is a lifestyle change. You need to build daily habits that keep your credit healthy for years to come. Check your credit score at least once a month using a free app.
Keep a close eye on your budget so you do not spend more than you earn. Having a small emergency fund can prevent you from running up credit card debt when things go wrong. A little planning goes a long way in keeping your credit safe.
When you make financial health a habit, your insurance rates will stay low. You will also enjoy lower interest rates on loans and better peace of mind. Taking care of your credit is one of the best things you can do for
Mastering Your Score for Lifelong Financial Peace
Many people spend years trying to fix their scores using basic advice. However, industry insiders use advanced strategies to speed up their results. Let us explore some of these expert methods so you can start saving money immediately.
The Statement Date Secret That Fast-Tracks Your Savings
Most people believe that paying their balance by the monthly due date is enough. While this avoids late fees, it might not help your overall credit rating. The secret lies in paying attention to your statement closing date instead.
Your credit card company reports your balance to the bureaus on this closing date, not the due date. If you carry a high balance on this day, it looks like you are using too much credit. This high usage is reported to the credit bureaus even if you pay the entire bill off a few days later.
To fix this, log into your account and find your statement closing date. Make a full or partial payment a few days before this date arrives. Doing this keeps your reported utilization rate low, which can immediately improve your overall rating.
The Magic of Rapid Re-scoring for Urgent Savings
If you are shopping for a new policy right now, you might not have months to wait for your score to rise. In this situation, you can ask about a process called rapid re-scoring. This is a special service where a lender or insurance broker submits proof of your recent payments directly to the credit bureaus.
Instead of waiting thirty to sixty days for a standard update, rapid re-scoring can update your file in just a few business days. This is highly useful if you have recently paid off a large debt or fixed a major error on your report. It can instantly drop your risk category and save you money on your upcoming renewal.
For more details on managing your overall coverage options, it is helpful to understand your policy limits. You should learn what is the difference between comprehensive and collision insurance to ensure you are not paying for protection you do not actually need.
Building a Healthy Mix of Financial Accounts
Credit bureaus love to see that you can handle different types of debt responsibly. Having only credit cards makes your profile look a bit one-dimensional. A healthy mix of installment loans and revolving credit shows that you are a reliable borrower.
Installment loans include things like car payments, student loans, or a home mortgage. Revolving credit refers to credit cards and retail accounts. You do not need to go into debt just to build this mix, but keeping existing loans in good standing is highly helpful.
If you only have credit cards, adding a small credit builder loan can diversify your profile. These are safe, low-cost financial products offered by local credit unions. They hold your payments in a savings account until the loan is paid off, reporting your good behavior the entire time.
Monitoring Your Financial Progress Safely
To maintain your success over the long haul, you must keep a close eye on your progress. You can easily access your information through resources supported by the Consumer Financial Protection Bureau. These official portals allow you to track your records without paying a penny.
Checking your own records does not count as a hard inquiry, so it will never hurt your score. Make it a habit to check your files at least once every month. This keeps you aware of any unexpected changes before they can impact your monthly rates.
When you look for trusted financial resources online, it is wise to consult specialized directories. You can find excellent advice and local agency reviews at trustpickshq.com to help guide your decisions. This makes your search for better financial tools much simpler.
Toxic Habits That Secretly Destroy Your Insurance Savings
It is incredibly easy to make a small mistake that damages your hard-earned credit rating. Many people fall into these traps without ever realizing the damage they are doing to their wallet. Let us look at some common financial pitfalls and how to avoid them.
The Danger of the Empty Credit Profile
Some people believe that staying completely out of debt is the safest path to financial peace. They pay cash for everything, avoid credit cards, and refuse to take out loans. While this sounds like a great way to live, it can actually backfire when you need insurance.
Having no credit history at all results in what lenders call a thin credit file. When an insurance company runs your background and finds nothing, they treat you as a high-risk driver or homeowner. This lack of data can force you to pay the exact same high rates as someone with a poor credit history.
To build a safe, positive history, you do not need to carry a balance or pay interest. Simply use a credit card for small monthly subscriptions, like a streaming service. Set up your card to autopay the balance in full every month, and you will build a great record for free.
The Co-signing Nightmare That Drags You Down
Helping a family member or close friend secure a car loan or credit card seems like a kind thing to do. However, co-signing is one of the quickest ways to ruin your own credit profile. When you sign that paper, you are taking full legal responsibility for that entire debt.
If your loved one misses a single payment, that negative mark goes directly onto your credit report. It does not matter if you were not the one driving the car or using the card. This drop in your score can cause your own insurance premiums to skyrocket overnight.
Before you agree to co-sign, consider the long-term cost to your own financial stability. It is often much safer to help them in other ways, such as helping them create a budget. Protecting your own score is necessary if you want to keep your household expenses low.
This danger is especially true when dealing with auto coverage. If a co-signed vehicle gets into an accident, you could face massive liability claims that exceed your policy limits. Knowing how to handle a lowball car insurance offer can save you from financial ruin if you ever find yourself in a legal dispute.
Missing the Quiet Warning Signs on Your Reports
Many people simply throw away collection letters, assuming they are scams or mistakes. This is a massive error that can haunt you for seven long years. A small, forgotten medical bill or utility charge can easily be sent to collections without your knowledge.
Once a collection agency reports this debt to the bureaus, your score will take a massive plunge. This single negative mark can wipe out years of good payment history in an instant. It can turn a preferred insurance rate into an expensive, high-risk policy at your next renewal.
If you receive a notice from a collection agency, deal with it immediately instead of hiding from it. Contact the collector and ask for written validation of the debt to verify it is yours. If it is accurate, try to negotiate a payment in exchange for removing the collection entry from your record.
If you are dealing with property protection, ignoring small details can be incredibly costly. For instance, many homeowners fail to realize that their coverage has hidden gaps. It is important to know if do non-flood zones require insurance so you do not lose your home to an unexpected storm.
The Store Card Trap at the Checkout Counter
We have all been asked to sign up for a store credit card to save ten percent on our purchase. While the discount sounds nice, these cards often come with very low credit limits. If you buy a few items, you will immediately use up a high percentage of your available credit.
These cards also carry incredibly high interest rates that can quickly wipe out any initial savings. Having too many retail accounts makes your credit profile look unstable to insurance companies. It is far better to have one or two major cards with high limits and zero balances.
Keep your credit applications clean and limited to major banking institutions. This disciplined approach shows insurers that you are a serious and stable consumer. It keeps your background checks looking clean and keeps your annual rates as low as possible.
Your Roadmap to Lower Rates: A Step-by-Step Action Plan
Step 1: Secure Your Credit Reports
Go online and request your free reports from the official credit bureaus. Print them out or save them as a PDF so you can read through them at your own pace. Highlight any mistakes, duplicate accounts, or late payments that seem incorrect.
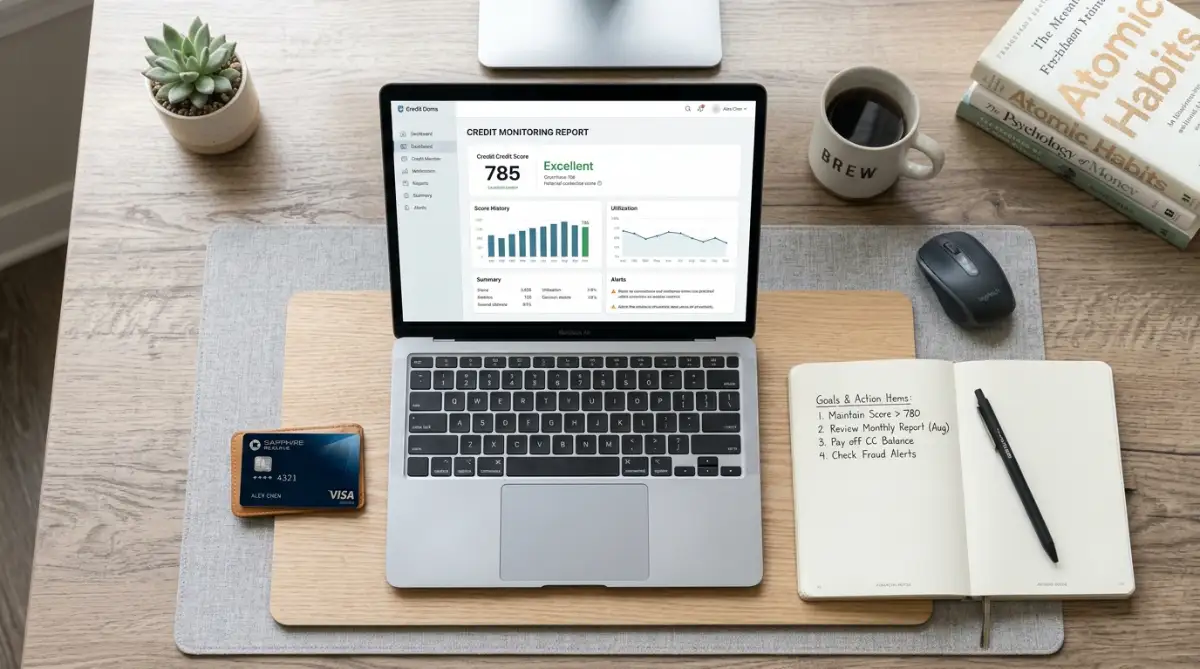
Step 2: Dispute Every Error
Write a simple dispute letter to the credit bureaus or use their online dispute tools. Provide copies of any bank statements or receipts that prove your payments were made on time. The law requires them to investigate these issues within thirty days, which can lead to quick improvements.
Step 3: Automate Your Payments
Set up automatic payments for your credit cards, utility bills, and loans. Even setting the system to pay just the minimum amount ensures you never get a late fee. This builds a consistent payment history that looks incredibly attractive to insurance providers.
To get additional support during this process, check the official guidelines from the Federal Trade Commission. They offer clear, step-by-step instructions on how to handle credit disputes safely. This ensures you do not fall victim to paid credit repair scams that promise unrealistic results.
Step 4: Pay Down High Balances
Focus on paying down your credit card balances until they are well below thirty percent of your limit. Use the snowball method by paying off your smallest balance first, or the avalanche method by targeting the highest interest rate. Whichever way you choose, reducing your debt will quickly boost your credit health.
Step 5: Shop for Better Insurance Rates
Once you see your score rise, do not stay silent with your current provider. Call your agent and ask them to recalculate your premium using your updated credit information. If they cannot offer you a lower rate, take your clean credit profile to other insurers to find a better deal.
This is highly useful when dealing with property coverage, where premiums are often quite expensive. If you live near water, you should check if you really need flood insurance in a low risk zone to see if you can lower your bills further. Making these smart adjustments can save you thousands of dollars over time.
I remember how stressed I felt when my monthly bills were piling up and my rates kept climbing. Taking charge of my credit felt like a daunting task, but it turned out to be the best decision I ever made. I want you to feel that same sense of relief when you open your next renewal notice and see a much smaller number.
Common Doubts Cleared: Your Questions Answered
How long does it take for a better credit score to lower my insurance rates?
It usually takes a few months for your improved score to reflect on your insurance bills. Most insurance companies only check your credit profile when your policy is up for renewal, which happens every six or twelve months. However, you can contact your agent mid-policy and ask them to run a credit re-evaluation immediately to speed up the process.
Do all states allow insurance companies to look at my credit history?
No, a few states have banned the use of credit scores for setting insurance rates. You should check with your local state insurance commissioner to see what rules apply to your area. In states where this practice is allowed, maintaining a strong credit score remains one of the best ways to keep your premiums low.
Will getting insurance quotes hurt my credit score?
No, shopping around for insurance quotes will not impact your credit score at all. When an insurance company reviews your credit, they perform what is called a soft inquiry. These soft pulls are completely invisible to other lenders and have zero effect on your credit health.
What is the absolute best credit utilization ratio for cheap insurance?
While keeping your balance under thirty percent is the general rule, keeping it under ten percent is ideal for the highest scores. Insurers want to see that you have plenty of available credit that you choose not to use. This indicates that you are financially secure and less likely to struggle with unexpected emergency costs.
Professional Disclaimer
This blog post is for informational and educational purposes only and should not be taken as professional financial or legal advice. Credit reporting rules and insurance laws can vary significantly depending on your location and specific situation. Always consult with a licensed insurance agent or a certified financial planner before making major changes to your credit accounts or insurance coverage.


