Navigating the Maze of Policy Choices
A few years ago, I stared blankly at two insurance policies spread across my kitchen table, completely overwhelmed by pages of fine print. I had no idea why one plan cost significantly more than the other, or if I was even paying for protection I actually needed. My head thundered with confusion, and that nagging sense of doubt kept me up way past midnight.
Choosing the wrong plan felt like setting money on fire while leaving my family exposed to unexpected financial shocks. That moment of frustration taught me that buying protection without understanding the underlying terms is a dangerous gamble.
Millions of people face this exact mental friction every single day. You log into comparison sites, look at rows of numbers, and feel your stress levels spike because every company claims to offer the best deal. This persistent guesswork robs you of your peace of mind. Instead of feeling secure, you feel anxious that a hidden clause might deny your claim when an emergency strikes.
The daily worry of making a costly mistake drains your mental energy and leaves you second-guessing every financial decision you make.
Unlocking the Blueprint of Policy Evaluation
Mastering how to break down different plans starts with looking past the monthly premium. Most people make the mistake of choosing the cheapest option without checking what is actually hidden inside the policy clauses. You need to look at your personal lifestyle and financial habits first.
Think of your daily routine, your health needs, or your driving habits before you look at any paperwork. When you match your actual risks with the policy limits, the right choice becomes much clearer.
Let me share a quick lesson from my own trials. I once chose a policy just because it had a very low monthly cost, only to find out later that the out-of-pocket deductible was ridiculously high. When a minor mishap occurred, I ended up paying entirely out of my own pocket because I never bothered to read the fine print. That painful realization taught me that cheap upfront costs often disguise heavy future burdens.
Always look at the total financial picture rather than just the initial price tag.
Decoding Deductibles, Limits, and Copays
Every solid policy rests on three main pillars that you must evaluate side by side. The deductible is the amount you pay before your provider kicks in their share of the expenses. If your deductible is too high for your current savings, a sudden emergency can wreck your budget instantly.
Policy limits, on the other hand, set the absolute maximum amount the provider will pay for a covered loss. If your medical bills or property damage go beyond that limit, you are legally responsible for the rest.
Copays and coinsurance dictate your daily sharing of medical or repair expenses. You want to strike a balance where these numbers fit comfortably into your monthly cash flow. Writing these figures down on a separate sheet of paper helps you visualize the real cost differences between competing offers. Never rely on memory alone when you are reviewing technical insurance terms.
Spotting Hidden Exclusions Before Signing
Insurance companies always list what they cover in bold letters, but what they leave out is usually buried deep in the exclusions section. You have to actively hunt for what is not covered by the plan. For instance, standard home or auto policies often exclude damage from specific natural events or unique mechanical failures unless you add an endorsement.
Skipping this step can lead to devastating surprises when you file a claim and discover a loop clause.
Take your time reading through the exclusion paragraphs line by line. If a term looks confusing or vague, look it up or ask an independent advisor to clarify its meaning. Transparency is your best defense against unexpected claim rejections. A few minutes of careful reading today can save you thousands of dollars and endless heartbreak tomorrow.
Evaluating Claims Processing and Customer Support
A policy can look amazing on paper, but it is practically useless if the provider has a terrible track record of paying out claims. Before you commit to any company, research their customer feedback regarding payout speeds and claim handling. Look for real user experiences that highlight how the company treats people during stressful situations.
A responsive support team makes all the difference when you are dealing with an accident or a property disaster.
Check if the provider offers easy digital tools to submit documents and track your claim status in real time. Waiting weeks for a simple reply adds unnecessary stress to an already difficult life event. Choose a company known for clear communication and fair, fast resolutions. Your future self will thank you for picking reliability over a slightly lower price.
Building Your Personal Policy Comparison Matrix
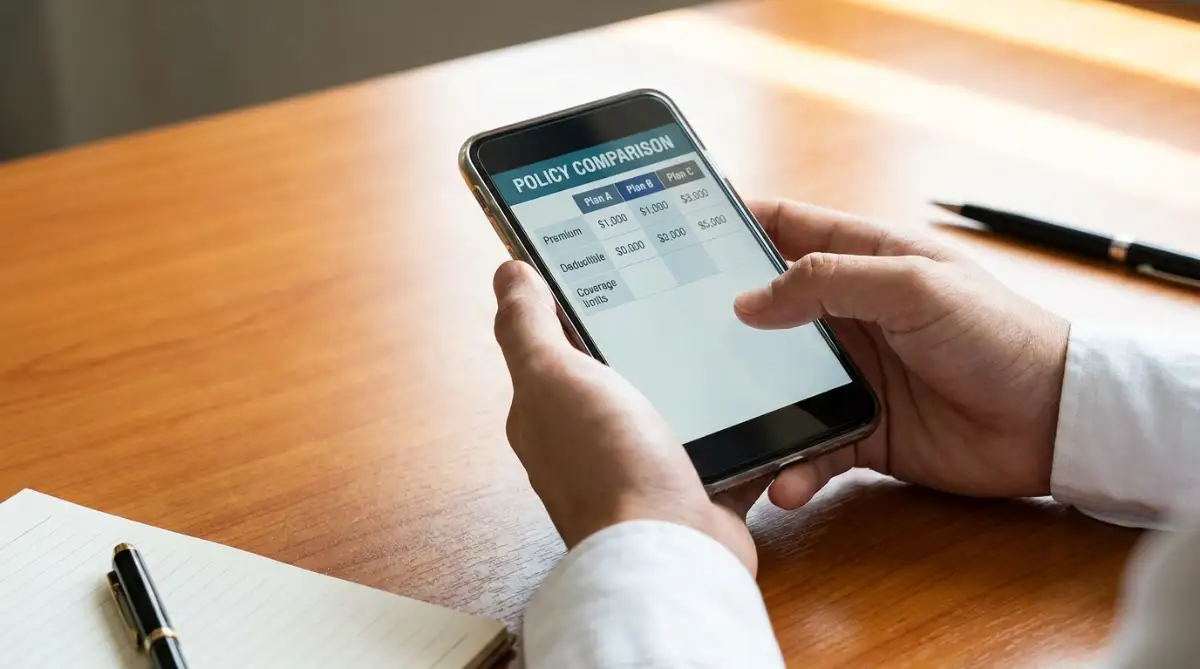
Creating a simple comparison table on your computer or notebook brings total clarity to your decision-making process. List your top three policy choices across the top columns and write down deductibles, premiums, limits, and exclusions in the rows. This visual layout strips away the marketing hype and lets you compare features objectively.
You will instantly spot which plan gives you the best value for your hard-earned money.
Review this matrix with your family members or anyone else who relies on your financial security. Getting a second set of eyes on the comparison ensures you have not overlooked any critical details. Once everything lines up cleanly on your grid, you can sign your chosen policy with absolute confidence and lasting peace of mind.
Mastering Advanced Policy Strategies
Unlocking the true potential of your policies requires looking far beyond standard coverage agreements. When you start comparing insurance coverage features side by side, you quickly realize that minor adjustments can yield major financial benefits.
Many savvy policyholders review their policy exclusions annually to ensure no unexpected gaps threaten their savings. This proactive habit keeps your protection aligned with your changing life circumstances.
Consider setting up a dedicated folder on your computer for all your insurance documents and policy updates. Whenever you receive an amendment notice from your provider, scan it immediately and update your personal spreadsheet.
If you want to dive deeper into managing your financial safety net, checking out resources on how much disability insurance do you need can offer incredible clarity. Staying organized transforms a confusing paperwork chore into a simple, manageable routine.
Avoiding Major Traps When Evaluating Plans
One of the most dangerous traps people fall into is assuming that a well-known brand name automatically guarantees a superior policy. Big marketing budgets do not translate to fair claim settlements or transparent terms. You must always read the actual contract language rather than trusting catchy television advertisements.
Ignoring the fine print often leads to bitter disappointments when a legitimate claim gets denied over a technicality.
Another frequent mistake is keeping the exact same coverage limits for years without adjusting for inflation or lifestyle growth. If your income and assets increase, your policy limits need to scale up proportionally to provide true protection.
For a deeper understanding of how these cost-sharing mechanics operate, you can review this guide on copays, coinsurance, and deductibles. Avoiding these careless oversights safeguards your financial stability over the long run.
Moving Forward with Confidence and Clarity
Taking control of your insurance choices empowers you to face the future with total peace of mind. By breaking down deductibles, checking exclusions, and organizing your documents, you eliminate guesswork from financial planning.
Building a secure lifestyle is an ongoing journey that rewards careful attention and smart decision-making.
Every step you take today toward better policy comprehension strengthens your overall financial armor. I always remind myself that taking ten extra minutes to read a contract clause is worth years of saved stress and protected savings. Take charge of your protection plan today and make choices that truly support your peace of mind.
Answers to Common Policy Questions
How often should I review my insurance coverage features?
You should examine your policies at least once a year or whenever you experience a major life milestone like moving, marriage, or buying a new vehicle. Regular checkups ensure your protection matches your current lifestyle needs.
Does a higher deductible always mean lower overall protection?
A higher deductible lowers your monthly premium, but it also increases your out-of-pocket expenses when a claim happens. You need to balance your monthly cash flow with your emergency savings before choosing high deductibles.
Why do two similar policies have such different price tags?
Companies weigh risk factors differently and offer distinct customer service models, policy limits, and add-on benefits. Looking closely at the exact feature breakdown reveals why one plan costs more than another.
Disclaimer
The information provided in this article is for educational and informational purposes only and does not constitute professional financial or legal advice. Insurance policies vary greatly depending on individual circumstances, provider guidelines, and regional laws. Always consult with a licensed insurance professional or financial advisor before making any major policy decisions or signing binding contracts.