My Personal Struggle with High Insurance Bills
I used to spend hours every single month staring at my bank statements. My insurance premiums felt like a giant vacuum cleaner sucking the life out of my savings. I was paying so much, but I didn't even know if the coverage was actually good. Every time I saw a new bill, my stomach would do a little flip of anxiety. I felt trapped because I thought "good" insurance had to be expensive.
My friends would tell me they found better deals, but I was always skeptical. I tried those big comparison websites, but they just felt like they were trying to sell me something. I wanted the truth, not a sales pitch. It felt like a constant battle between my wallet and my peace of mind. I just wanted a simple way to know which company would actually help me without charging a fortune.
The stress of overpaying was real and it affected my daily life. I had to cut back on small things I enjoyed, like my weekend coffee or a new book. It sounds small, but it adds up when you feel like you are being overcharged. I knew there had to be a better way to navigate this confusing world of policies and fine print. That is when I decided to change my approach and look at what real people were saying.
The Emotional Weight of Financial Pressure
Most people don't realize how much a high insurance bill can weigh on your mind. It is not just about the money; it is about the feeling of being taken advantage of. When you work hard for every dollar, seeing it go toward a massive premium feels unfair. This constant worry creates a cloud over your financial goals. You might want to save for a home or a trip, but the insurance monster keeps eating your budget.
This pressure often leads to a "set it and forget it" mindset, which is exactly what big companies want. They hope you are too tired or too busy to look for a better deal. I was in that cycle for years, feeling frustrated and helpless. It makes you feel like you aren't in control of your own life. You start to think that maybe cheap insurance just doesn't exist for people like you.
But the reality is that the information is out there. The problem is that it is often buried under marketing fluff and complex jargon. People are struggling every day to find a balance between price and protection. They want to feel safe without going broke. I finally realized that the key wasn't in the advertisements, but in the experiences of others.
Why I Stopped Trusting Ads and Started Reading Feedback
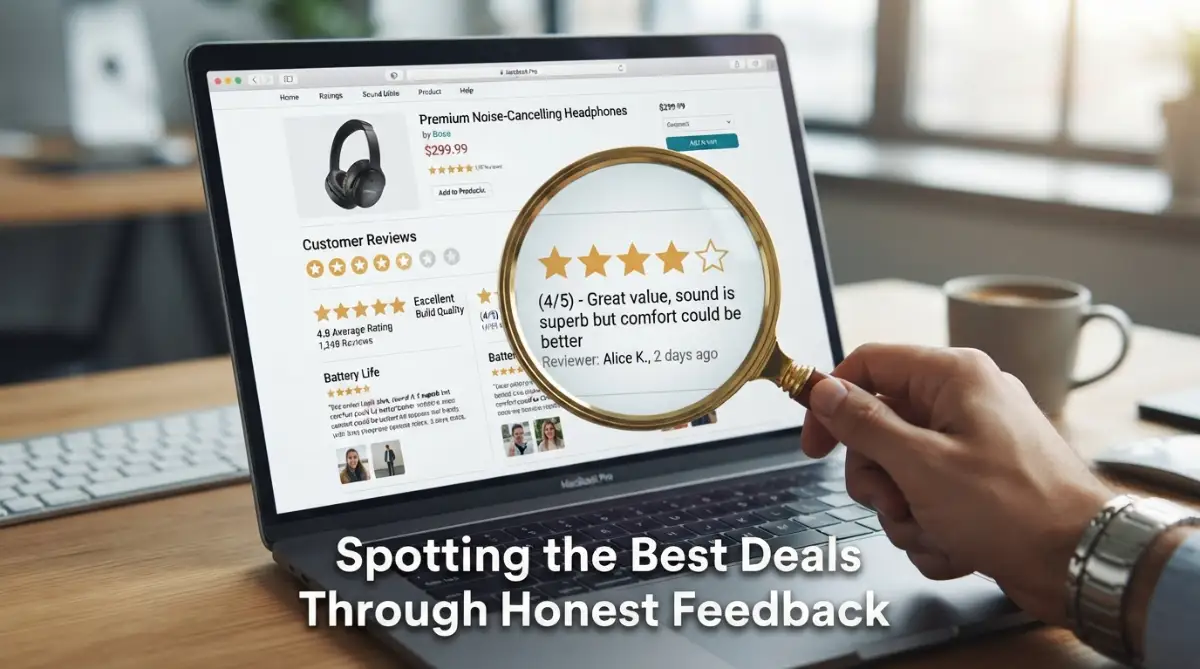
I used to think that the biggest companies with the most commercials were the best ones. I was wrong. I spent a whole weekend reading hundreds of stories from people just like me. I realized that a flashy ad doesn't mean they will pay your claim quickly. In fact, some of the most expensive companies had the worst feedback from real customers.
I started looking for patterns in the comments people left online. I didn't just look at the star rating. I looked at the "why" behind the rating. Was the company hard to reach? Did they raise the price for no reason? This was a huge turning point for me. I began to see a clear path toward saving money while still keeping good coverage.
Pro Tip: I used to make the mistake of only reading the five-star reviews. I thought they were the most helpful. Now, I always check the three-star reviews first. They usually give the most balanced view of what it is really like to work with the company. This small change in how I read feedback helped me avoid two companies that looked great on paper but were a nightmare in reality.
Decoding the Language of Real Customer Experiences
When you look at reviews, you have to be a bit of a detective. Some reviews are just people complaining about things that aren't the company's fault. But when you see five different people saying the "customer service is slow on Tuesdays," that is a real sign. I started making a list of the companies that actually cared about their users.
I noticed that the cheapest companies often don't spend a lot of money on TV ads. Instead, they focus on keeping their current customers happy. This was a revelation for me. I found that I could get the same level of protection for a fraction of the cost just by switching to a company that relied on word-of-mouth. It felt like I had found a secret club for smart savers.
Identifying Genuine Feedback Versus Bot Generated Text
One of the biggest hurdles I faced was figuring out which reviews were real. There are a lot of bots out there these days. I learned to look for specific details. A real person will mention a specific situation or a name of an agent. A bot will just say "Great service, very happy!" over and over again. This skill is vital if you want to find the best rates.
I also looked at the dates of the reviews. If a company had 500 perfect reviews in one week and then nothing for a month, I knew something was fishy. Honest companies have a steady stream of feedback over a long time. I focused my search on those steady performers. This kept me from falling for "too good to be true" deals that would have cost me more in the long run.
The Power of Comparing Claims Processing Times
Finding a cheap price is only half the battle. I wanted to know if the company would actually pay if I had an accident. I searched specifically for reviews that mentioned the "claims process." Some companies are very cheap but they make it nearly impossible to get your money back. That is not a deal; that is a trap.
I found a few smaller providers that had amazing reviews for their speed. People were saying they got their checks within days. To me, that was worth more than a few dollars of savings. However, the best part was that these companies were often cheaper than the "big guys" anyway. It was a win-win situation that I never would have found without deep-diving into user stories.
Here is a great video that explains how to compare different plans without getting overwhelmed. It really helped me understand the basics before I started reading the reviews.
Looking for the "Hidden Fees" in User Stories
Another thing I searched for in reviews was any mention of hidden fees. Some insurance providers lure you in with a low monthly price but then charge you for every little thing. I read stories of people being charged for "account maintenance" or "paper statement fees." I made sure to cross those companies off my list immediately.
By reading about other people's mistakes, I saved myself from making them. I found that the most honest companies were very upfront about their pricing. Their customers often praised them for having a "no-surprises" bill. This is the kind of transparency that makes a company worth your time and money. I learned to value honesty just as much as I valued a low price.
How to Use Comparison Tools Effectively
I didn't just use one review site. I used several. I found that different sites often have different types of users. Some are more for professionals, while others are for everyday families. By looking at a variety of sources, I got a full picture of each company. It was like putting together a puzzle where the final image was a much lower monthly bill.
I also used tools that let me see a side-by-side comparison of the top-rated companies. This allowed me to see exactly what I was getting for my money. I could see that Company A had better dental coverage, while Company B was better for car accidents. This level of detail is something you can only get when you combine data with real-world feedback.
The Myth of the "Brand Name" Insurance
I used to think that if I hadn't heard of a company on the news, they weren't safe. This is a total myth. Many smaller, regional companies have much higher customer satisfaction scores. They don't have to pay for expensive stadiums or celebrity spokespeople. They pass those savings on to people like you and me.
I found that these "unknown" companies often provide a much more personal experience. When I called one of them to ask a question, a real person answered the phone in less than a minute. That never happened with my old, expensive provider. My research showed me that being a "big name" often means you are just a number in a giant database. I preferred being a valued customer at a smaller firm.
Setting Your Own Priorities Before You Shop
Before I started my final search, I wrote down what was most important to me. For me, it was a low deductible and a fast mobile app. Other people might care more about 24/7 roadside assistance. By knowing my own needs, I could filter through the reviews much faster. I stopped wasting time on companies that didn't offer what I actually needed.
This step is something many people skip. They just look for the lowest number. But the lowest number doesn't matter if the service doesn't fit your life. I found the cheapest insurance that specifically fit my lifestyle. That is the true definition of a bargain. It felt like the insurance was finally working for me, instead of the other way around.
Reality Check: Is the Cheapest Always the Best?
I have to be honest here. I found some incredibly cheap options that were clearly terrible. The reviews were full of people saying their calls were never returned. This is why you cannot just sort by "price: low to high." You have to sort by "value." Value is the perfect mix of a low price and a company that actually does its job.
I learned to be wary of companies that were significantly cheaper than everyone else. If everyone is charging $100 and one company is charging $20, there is a catch. Usually, the catch is that they won't pay your claims. My goal was to find the company that was $10 or $20 cheaper than the average but still had glowing reviews. That is where the real savings live.
The Role of State Regulations in Your Search
One thing I discovered is that insurance prices vary wildly depending on where you live. Some companies that are great in one state might be expensive in another. I made sure to look for reviews from people in my own area. This gave me a much more accurate idea of what I would actually pay.
Local reviews are a goldmine of information. They can tell you about how the company handles local issues, like storm damage or specific traffic laws. I found a local provider that had a tiny office just ten miles from my house. They ended up having the best rates and the most helpful reviews from my neighbors. It really pays to think locally when you are searching for a global service.
Learning from the Mistakes of Others
Every bad review I read was a lesson for me. If someone said they were hit with a price hike after six months, I looked into why. Often, it was because they didn't read the terms of an "introductory rate." I learned to ask the right questions before I signed anything. I would ask, "Is this price guaranteed for the whole year?"
This proactive approach came directly from reading user feedback. It gave me a list of "red flags" to watch out for. I felt so much more confident talking to insurance agents. I wasn't just a confused customer anymore; I was an informed buyer. This shift in power felt amazing and it all started with those honest reviews.
My Realization About Long-Term Savings
I used to think that saving $10 a month wasn't worth the effort of switching. I was so wrong. When I found my new plan, I saved about $45 a month. Over a year, that is $540. Over five years, that is $2,700! That is a huge amount of money that I was just throwing away before.
When you look at it that way, the few hours I spent reading reviews were the most profitable hours of my year. It is like giving yourself a small raise that is tax-free. I wish I had done this years ago. If you are on the fence about looking for a new plan, just think about what you could do with an extra $500 every single year.
How Reviews Help You Negotiate
Believe it or not, I actually used reviews to get a better deal from my old company first. I called them up and said, "I am seeing reviews for Company X that say they offer the same coverage for $30 less. Can you match that?" While they couldn't match it perfectly, they did offer me a discount to stay.
Even though I eventually switched anyway, it showed me that information is power. When you know what the market looks like, you don't have to accept the first price you are given. You can speak with authority because you know what other people are paying. This alone made the whole process worth it for me. It changed the way I look at all my monthly bills, not just insurance.
Why You Should Leave Your Own Reviews
After I found my new, cheap insurance, I made sure to leave a review myself. I wanted to help the next person who was in my shoes. I shared exactly how much I saved and what the sign-up process was like. It felt good to contribute to the community that helped me save so much money.
Reviews are a circular economy. We all benefit when we share our honest experiences. If you find a great deal or a terrible one, speak up. Your words might be the exact thing someone else needs to read to fix their financial stress. I am now a firm believer that the best financial advice doesn't come from experts in suits, but from regular people sharing their truth online.
Mastering the Hidden Secrets of Smart Insurance Shopping
Building on what we discussed earlier, finding the absolute best price requires a bit of insider knowledge. I learned that simply looking at the sticker price is a rookie move. To truly win at this game, you need to understand how companies use your data to set your rates. One of the most effective things I did was look into how my credit history impacted my premiums.
Many people don't realize that insurance companies often use a "credit-based insurance score" to decide how much you pay. If you want to get the lowest possible rate, it helps to keep your finances in order. While I was researching, I found that improving your credit score can actually lower your insurance costs significantly over time. It is all connected, and the reviews I read confirmed that people with better financial habits always got the best deals.
Another trick I picked up from reading hundreds of comments was the "loyalty trap." Most people think staying with the same company for ten years will save them money. The reviews told a very different story. Real users often complained that their rates went up every single year despite having no accidents. This taught me that being a "loyal" customer often means you are paying a "lazy tax."
Using Technology to Slash Your Monthly Payments
While browsing through detailed user feedback, I kept seeing people mention "telematics" programs. These are the small devices or apps that track how you drive. At first, I was a little worried about my privacy. However, the reviews from other budget-conscious drivers changed my mind. They showed me that if you are a safe driver, you can save up to thirty percent just by letting the company see your driving habits.
I decided to try it out, and it made a huge difference. I stopped speeding and started braking more gently. Not only did my insurance get cheaper, but I also felt safer on the road. It is a great example of how using modern tools can put money back in your pocket. You can check the official guidelines on how these programs work at the National Association of Insurance Commissioners to see if it is right for you.
You should also look for reviews that mention mobile app functionality. In today's world, you don't want to spend an hour on hold just to change your address. I found that the companies with the best apps usually have the most satisfied customers. A good app lets you upload photos of an accident and start a claim in minutes. This kind of efficiency is a major part of the "value" I mentioned before.
The Art of Strategic Policy Bundling
One of the most common pieces of advice I saw in reviews was about "bundling." This is when you buy your car, home, and life insurance from the same place. But here is the secret I found: bundling isn't always the cheapest way. Sometimes, companies give you a discount on one policy but overcharge you on the other.
I read a story from a woman who saved five hundred dollars by actually unbundling her policies. She found a great deal on car insurance with one company and an even better deal on her home insurance with another. This taught me to always check the total price, not just the discount percentage. You have to do the math yourself because the companies won't do it for you.
When you are looking at different types of coverage, it is easy to get overwhelmed. For example, if you are self-employed, you might be looking for affordable health insurance for freelancers alongside your other policies. The key is to look for reviews from people who have the same career or lifestyle as you. Their experiences will be much more relevant to your specific needs.
My Strategy for Uncovering "Hidden" Discount Codes
Did you know that your college degree or your job could save you money on insurance? I found this out by reading a review from a teacher who got a "professional discount." I started calling companies and asking if they had discounts for my specific line of work. It turns out many companies offer lower rates for engineers, teachers, and even government employees.
I also looked for reviews that mentioned "affinity groups." These are organizations like alumni associations or professional unions. If you belong to one, you might qualify for a group rate that is much lower than the public price. It takes a little bit of extra research, but the savings are well worth it. I never would have known to ask about this if I hadn't spent time reading those long, detailed reviews from other users.
Myth vs. Reality: What the Reviews Taught Me
- Myth: You always need a local agent to get the best service.
- Reality: Online-only companies often have better customer service ratings and much lower prices.
- Myth: Older companies are always more stable.
- Reality: Newer tech-based companies often have better financial backing and faster claims processing.
- Myth: You should always pick the plan with the lowest deductible.
- Reality: Raising your deductible slightly can save you a fortune in monthly premiums, as long as you have some emergency savings.
The Danger of Chasing the "Bottom Dollar"
I need to warn you about something I saw quite often in the reviews. Some people got so obsessed with finding the lowest price that they ended up with "ghost coverage." This is insurance that looks good on paper but has so many exclusions that it is basically useless. If a company is fifty percent cheaper than everyone else, they are usually cutting corners somewhere.
I read heartbreaking stories of people who thought they were covered for water damage, only to find out their "cheap" policy specifically excluded it. This is why you must read the reviews that mention "claim denials." If you see a pattern of a company denying claims for small technicalities, stay away. Saving twenty dollars a month is not worth losing twenty thousand dollars when you actually need help.
This is especially true when looking at life insurance. You have to be careful and understand the truth about cheap life insurance before you sign up. Sometimes, these policies are so limited that they don't provide the peace of mind you are looking for. Always balance the price with the actual protection you are getting.
Why You Must Avoid "Automatic Renewals" Without Checking
One of the biggest mistakes I almost made was letting my policy renew automatically. Companies often use an algorithm that predicts who is likely to switch and who is likely to stay. If the algorithm thinks you are too busy to shop around, they might slowly increase your rate. This is called "price optimization," and it is a real problem.
I read a review from a man who found out he was paying double what a new customer was paying for the exact same coverage. This made me so angry that I immediately set a reminder on my phone to shop around every six months. You don't always have to switch, but you should always check. Just knowing that you are looking can sometimes prompt your current company to give you a "retention discount."
The Mistake of Ignoring "Customer Satisfaction" Scores
A lot of people focus only on the price and the coverage, but they forget about the people they will have to talk to. If you are in a car accident, you are already stressed. The last thing you want is to deal with a rude or unhelpful claims adjuster. I made sure to look at the J.D. Power customer satisfaction rankings to see which companies treated people with respect.
The reviews often mentioned specific names of helpful agents or complained about a "robotic" support system. I chose a company that had a reputation for being empathetic and kind during difficult times. This didn't cost me any extra money, but it gave me so much more peace of mind. Remember, you are buying a service, not just a piece of paper.
Forgetting to Update Your Policy After Life Changes
Another common pitfall is keeping the same policy even after your life changes. Did you get married? Did you move to a safer neighborhood? Did you start working from home? All of these things can lower your rates. I found a review from a guy who saved two hundred dollars just by telling his company he was driving fewer miles because he started working remotely.
If you don't tell them, they won't ask. You have to be your own advocate. Check your policy every time you have a major life event. Even something as small as installing a security camera at your front door can lead to a discount. Use the reviews to see what kinds of things other people are getting rewarded for, and then see if those apply to you.
Not Checking the "Financial Strength" of the Company
This sounds like a boring topic, but it is actually very important. You want to make sure the company has enough money to pay everyone's claims if there is a big disaster. I used sites like A.M. Best to check the financial health of the companies I was considering.
I read a review from someone whose small insurance company went bankrupt after a major storm. They were left with no coverage and no way to get their money back. It was a total nightmare. Now, I only look at companies with an "A" rating or higher. This ensures that the "cheap" insurance I found will actually be there when I need it most.
Why Skipping Disability Coverage Is a Huge Risk
While I was looking for car and home insurance, I realized many people forget about their ability to earn a living. I saw several reviews from people who had an accident and couldn't work, but they didn't have the right coverage. It made me realize that I needed to look into how much disability insurance you need to protect my family.
It is easy to think "it won't happen to me," but the reviews prove otherwise. Being prepared for the unexpected is part of a smart financial plan. I found that adding a small disability rider was actually very affordable when I used the same review-based search method. It is all about looking at the big picture of your life and your finances.
Finding Confidence in Your Financial Decisions
After weeks of research and reading hundreds of reviews, I finally felt like I was in the driver's seat. I wasn't just guessing anymore. I knew exactly why I chose my company and why I was paying a certain price. This feeling of confidence is worth more than the savings themselves. I stopped worrying about my bills because I knew I had the best possible deal.
I want you to feel that same way. You don't have to be a financial expert to save money. You just have to be willing to listen to the experiences of others and do a little bit of homework. The information is right there at your fingertips. All you have to do is look for it and use it to your advantage.
Your Simple Action Plan for Today
I know all of this information can feel like a lot to take in. But you don't have to do everything at once. Start by picking one policy you feel you are overpaying for. Go to a few review sites and see what people are saying about the top three competitors. Just that one small step can start you on the path to saving hundreds of dollars.
Once you see how easy it is to find a better deal, you will want to do it for all your bills. It becomes like a game where you are the winner every time. I am so glad I took the time to read those reviews, and I know you will be too. Your future self will thank you for the extra money you have in your bank account.
I truly believe that anyone can take control of their finances with the right information. My own journey from being stressed and broke to feeling secure and smart was all thanks to these honest reviews. I am now saving more money than I ever thought possible, and I feel so much lighter every day. I really want you to experience that same sense of relief and excitement.
Start your search right now and don't stop until you find a price that makes you smile. You deserve to keep more of your hard-earned money. I promise that once you find that first great deal, you will never look at insurance the same way again. Go out there and get the savings you deserve!
Common Questions About Finding Cheap Insurance
Can I really trust online reviews for insurance?
Yes, but you have to be smart about it. Look for detailed stories rather than short praise. Real people will explain exactly what happened during a claim or a phone call. If you see the same praise or complaint in many different reviews, it is likely the truth.
Will my rates go up if I check other prices?
No, simply looking for a new quote does not affect your current rate or your credit score. Most insurance companies do a "soft pull" on your credit, which is invisible to lenders. You can shop as much as you want without any fear of hurting your record.
Is it better to go with a big name or a small company?
It depends on what you value more. Big companies have more resources and often better apps. Small companies often have lower prices and more personal service. Use reviews to see which style fits your personality better.
How often should I switch my insurance provider?
I usually recommend checking prices every six months or at least once a year. You don't always have to switch, but the market changes constantly. Regular checking ensures that you are always getting the fairest price available.
What should I do if a cheap company denies my claim?
First, read your policy carefully to see if the denial was fair. If not, you can file an appeal or contact your state's insurance department. Reviews often contain tips from other users who successfully fought a claim denial, so look there for advice.
Disclaimer: This article is for informational purposes only and does not constitute financial or legal advice. Insurance regulations and prices vary by location and individual circumstances. Always read your specific policy documents and consult with a licensed insurance professional before making any financial decisions. We are not responsible for any actions taken based on the information provided in this post.